For most people, buying a first home ranks among the biggest milestones of a lifetime, and it is also one of the easiest to mishandle.
A real estate professional with more than ten years of experience, working directly with buyers, closing transactions, and getting through market cycles, describes a familiar pattern: excitement that slowly turns into heavy stress. The remedy, in this professional’s view, is a structured and strategic plan. Broken into ten stages, the path from renter to confident homeowner becomes manageable and rewarding. The same protocol applies whether the target is a suburban single-family house, an urban townhome, or an investment property, and it protects the buyer’s capital while setting the stage for long-term wealth accumulation.
The first stage takes place before any online listing or open house. It is a frank audit of your financial standing. Over ten years in the industry, this professional has watched too many eager buyers fall for properties far beyond their means. The audit starts with a tally of verified income, recurring monthly spending, and outstanding debts, including student loans, auto loans, and credit card balances.
From those figures comes your debt-to-income ratio, or DTI. This number gives a realistic picture of the mortgage payment you could carry without straining your lifestyle, and lenders look at the very same metrics when judging creditworthiness. Running the calculation early lets you set a workable budget for home loans and spares you the disappointment of touring houses you could never finance over the long run.
The second stage is building the down payment, which remains one of the biggest obstacles for first-time buyers. Conventional loan programs typically look for 20% down, a level that removes the extra monthly expense of private mortgage insurance, known as PMI. Still, a range of federal, state, and local assistance programs lets qualified buyers obtain financing with as little as 3% to 5% down. Beyond ordinary savings accounts, shrewd buyers look at other ways to accumulate funds, such as withdrawals from employer-sponsored retirement accounts or specialized first-time homebuyer savings grants. A cushion built early means that closing costs, appraisal fees, and earnest money deposits never catch you unprepared when they come due.
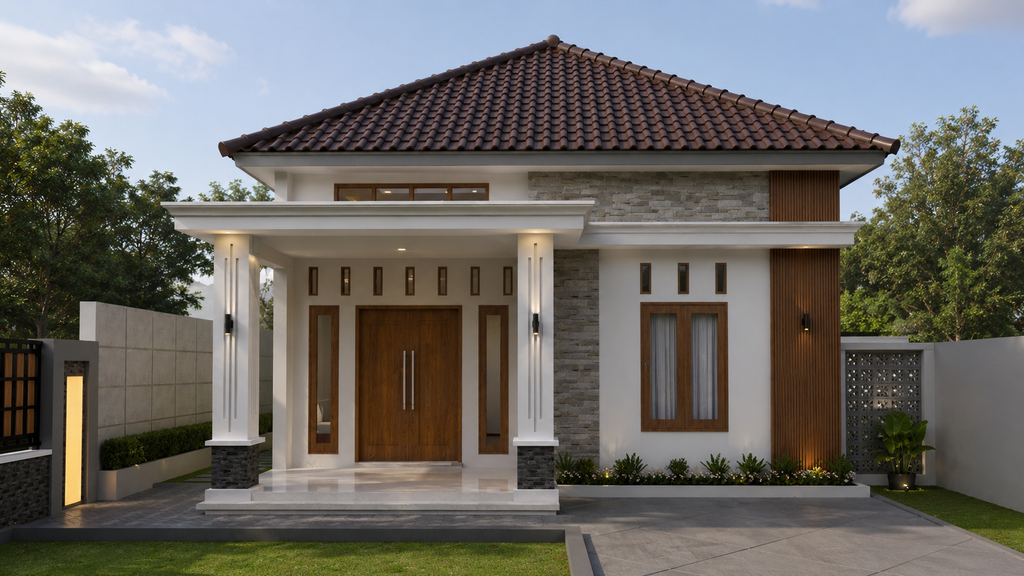
Third comes market research. Real estate is hyper-local, so national economic headlines seldom explain what is happening in one particular neighborhood. Thorough research helps separate inflated hype from genuine value. Buyers should study recent comparable sales, known as comps, along with historical price appreciation rates and planned municipal infrastructure projects. New transit lines, commercial developments, and school district expansions all fall into that last category, and each can shift property values down the road. Deep familiarity with inventory trends and neighborhood dynamics becomes a major advantage later, when it is time to judge property values and build a competitive offer.
The fourth stage is mortgage pre-approval, and it must come before house hunting. Touring homes before talking to a loan officer is among the most common beginner mistakes. A formal pre-approval differs completely from a casual online pre-qualification, because an underwriter rigorously verifies your tax returns, W-2s, and credit history. Buyers can compare interest rates, loan origination fees, and closing costs by shopping among multiple mortgage brokers, credit unions, and national banks. With an official pre-approval letter in hand, you show sellers that you are a serious, financially vetted buyer who can close a transaction smoothly and efficiently.
Fifth, define the property criteria that cannot be compromised. With the budget locked in, you need a crystal-clear picture of what your future home must offer. Separate the absolute “must-haves” from the “nice-to-haves,” weighing geographic location, square footage, architectural style, bedroom and bathroom counts, school district ratings, and daily commute times. Do you require a fenced backyard for pets, a dedicated home office, or a two-car garage? Settling these questions in advance prevents decision fatigue during the search and lets your real estate agent assemble a targeted list of properties that truly suit your lifestyle.
The sixth stage is the search itself. Once you hold a pre-approval letter and a defined checklist, active house hunting can begin. Digital real estate platforms make it possible to monitor new inventory every day. Weekend open houses add firsthand looks, and a seasoned buyer’s agent with deep local expertise rounds out the team. A great agent offers valuable insight into neighborhood nuances, uncovers off-market opportunities, and spots potential red flags during walkthroughs that an untrained eye might easily miss. At every property, take detailed notes and photos so your Impressions stay clear as the options pile up.
Seventh, structure and submit the purchase offer. When one property checks every box, the next task is a compelling purchase agreement. Working with your agent, analyze recent neighborhood sales data to arrive at a fair market offer price. The contract should spell out purchase price contingencies, requested seller concessions, earnest money deposit amounts, and proposed closing timelines. After reviewing your terms, the seller may accept, reject, or counter-offer. Once both sides agree and the contract is executed, you open escrow, and the earnest money goes into a secure trust account while the transaction moves toward closing.
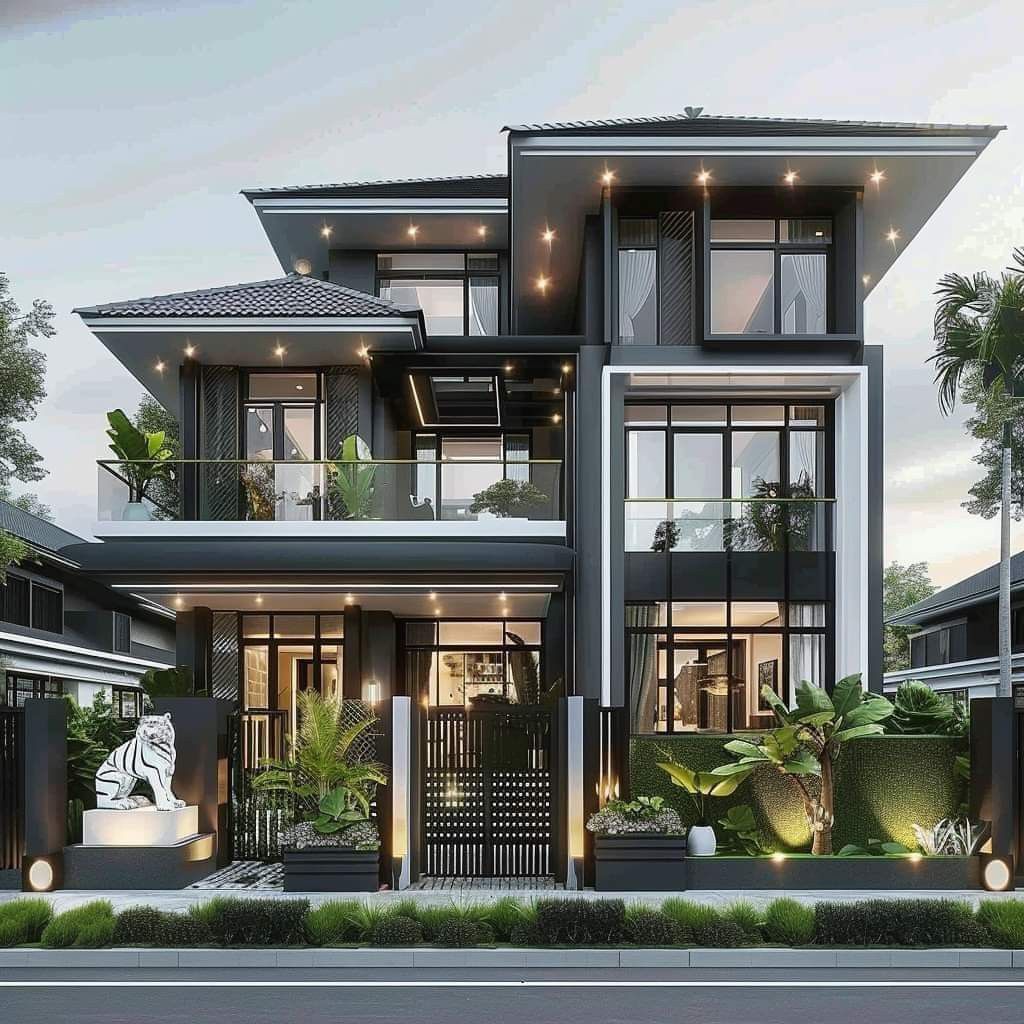
The eighth stage is rigorous due diligence and property inspection. An accepted contract does not mean the deal is done. Protecting the investment calls for comprehensive due diligence during the contractual contingency period. A certified home inspector should evaluate the property’s structural integrity, roof condition, electrical systems, plumbing, HVAC units, and foundation. At the same time, review municipal zoning documents, title commitments, and homeowners association, or HOA, rules. If the inspection uncovers significant mechanical or structural defects, those findings give you leverage to negotiate repair credits or price reductions. Under the inspection contingency, you can also walk away safely.
Ninth, finalize mortgage underwriting and loan terms. Once due diligence is satisfied, the lender moves from conditional pre-approval to final underwriting approval. Any updated financial documentation the lender requests should go in Immediately, since delays on your side can postpone closing. At least three business days before closing, review the Closing Disclosure, or CD, with care. This document lays out your exact loan amount, final interest rate, monthly principal and interest breakdown, property taxes, insurance premiums, and total closing costs. When every figure matches your expectations, you reach the final signing table without unpleasant financial surprises.
The tenth and final stage is settlement day. You meet with a closing attorney or escrow officer to sign the final loan documents, pay the remaining down payment and closing costs by wire transfer or cashier’s check, and officially transfer the property title into your name. When the county records the deed, the keys to your new front door are yours. At that point you are a homeowner, positioned to build long-term equity and stability.
To sum up, the route runs from an honest look at your finances through down payment planning, market research, pre-approval, a defined wish list, the search, the offer, inspections, final underwriting, and the settlement table. Each stage prepares the ground for the next, and skipping one puts the whole purchase at risk.
If this breakdown helped, hit the subscribe button so you stay current on new videos. Give the video a like if you found it useful, and switch on the notification bell so the latest updates reach you the moment they go live.”