Every month, a renter writes a check, and every month that money lands in someone else’s account and never comes back.
That fact sits at the center of a question I have heard from hundreds of families during more than ten years of advising property buyers: keep renting, or finally buy? The rent payment feels routine, even comfortable. It is also an expense that returns nothing.
Buying an apartment is about more than acquiring four walls and a roof. It is a way of building your financial future. In fast-growing urban corridors, the shift is already visible. Demand for modern residential units has climbed sharply as more people recognize what property ownership is worth over the long run. What follows explains why moving from tenant to owner remains one of the strongest financial decisions available today.
Start with wealth. Rent is a recurring operating expense, in the same category as utility bills or groceries. It covers shelter for the present and leaves nothing behind for the future. An apartment purchase works differently, serving both as a forced savings mechanism and as an appreciating asset. Each mortgage payment adds to your equity, converting what would have been a liability into net worth. Real estate has historically grown faster than ordinary inflation, so the asset gains value even while you sleep. Over a ten-year horizon, the distance between a homeowner’s net worth and a perpetual renter’s net worth becomes staggering.
Then consider the cost of staying put. Anyone who has rented for more than a couple of years knows the anxiety that arrives with each annual lease renewal. Landlords raise rates to keep pace with market pressures, and every increase eats into the amount you can save. A fixed-rate home loan changes that picture by locking in your monthly housing outlay. Rental prices may climb across the board, but your mortgage commitment stays predictable. When the loan term ends, you enter a liberating phase of rent-free, mortgage-free living, which sharply reduces what you must cover in retirement.
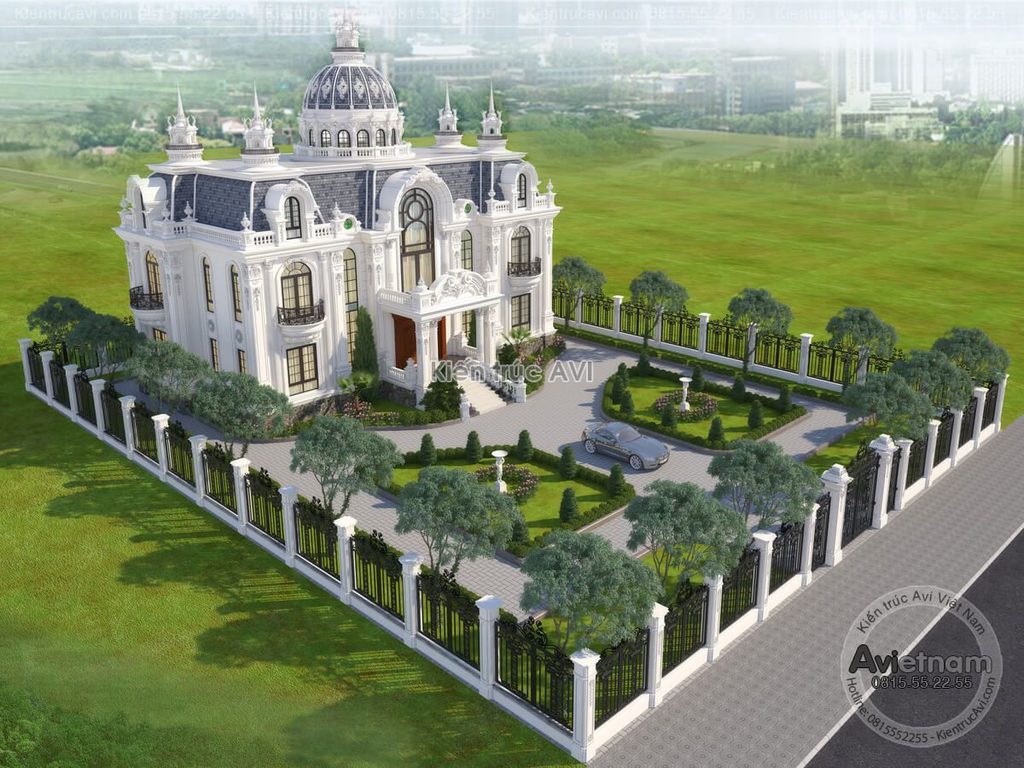
Stability is another factor. Having to relocate every few years because a landlord sells the property or raises the rent beyond reason is exhausting. Owning a home gives a family a permanent anchor and a deep sense of psychological steadiness. Ownership also brings the freedom to shape the space itself. Renters face a long list of restrictions: no painting the walls, no changing fixtures, no upgrading custom storage. An owner can completely gut and renovate the kitchen, install premium hardwood flooring, or reconfigure the layout as life evolves, all without needing anyone’s permission.
Governments around the world also encourage ownership through structural tax incentives. Rental payments offer zero tax relief, whereas home loans frequently unlock deductions on both interest outlays and principal repayments. Those provisions lower your annual taxable income and, in effect, subsidize a portion of your housing investment. A mortgage also instills a high degree of financial discipline. It forces structured budgeting, which naturally lifts your credit score over time. A robust credit history lowers borrowing costs for future financial milestones and compounds your overall economic leverage.
A larger property opens the door to passive income. Invest in a spacious 2 BHK or 3 BHK apartment in a high-demand urban pocket, and you keep the flexibility to monetize any space you do not need. Rental yields in thriving residential micro-markets remain exceptionally strong. If your lifestyle changes, or your family relocates temporarily, the property can easily pivot into a cash-flowing asset that covers its own mortgage and still generates net positive monthly income.
Safety and shared amenities round out the case. Standalone rental houses often lack the robust security infrastructure that modern families require. Modern apartment complexes, by contrast, feature gated perimeters, 24/7 security personnel, advanced surveillance systems, and controlled access points. Community living also grants turnkey access to lifestyle amenities that would cost a fortune to build on your own: fully equipped fitness centers, landscaped jogging tracks, swimming pools, and dedicated children’s play areas. Buying into a well-planned development means trading the isolation and maintenance headaches of an independent house for a vibrant, hassle-free neighborhood.
Three questions come up again and again. Why is buying an apartment better than renting? Buying builds long-term equity, protects you against rising inflation, offers tax benefits, and gives you complete freedom to customize your living space. Renting offers short-term flexibility but produces zero financial return.
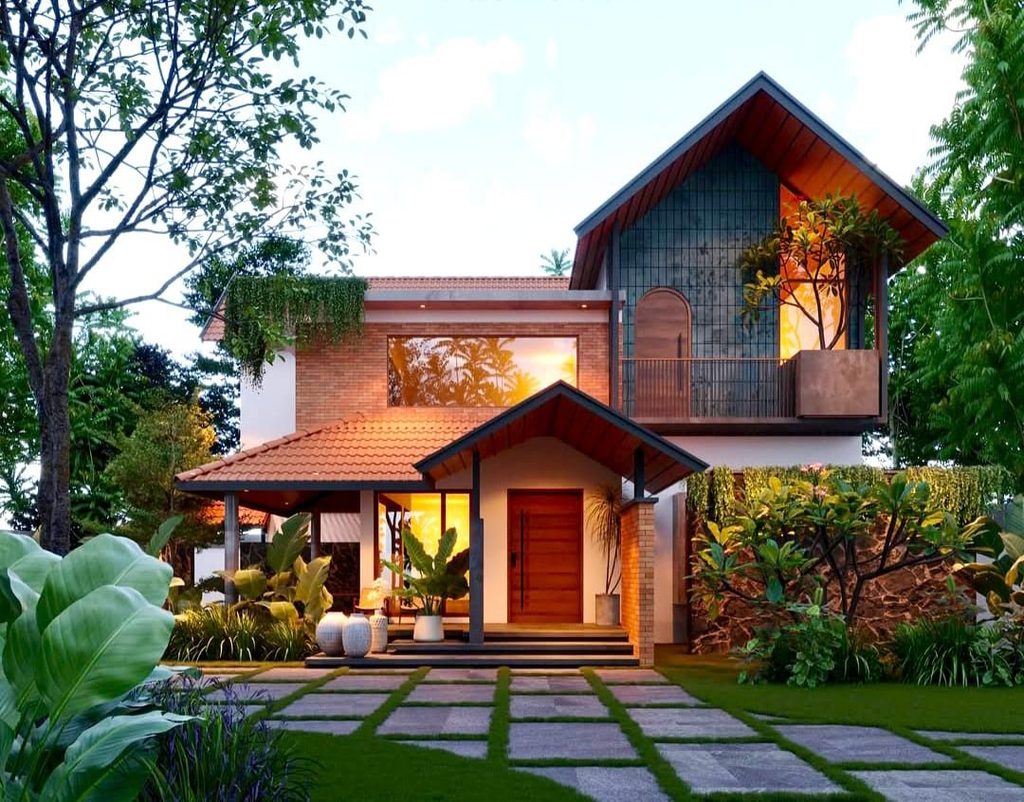
What is the biggest advantage of buying a home over renting one? The biggest advantage is asset accumulation. Your monthly housing payment stops being a pure expense and becomes a forced savings vehicle that appreciates in value over time.
What are the main lifestyle benefits of apartment living? Apartment living provides enhanced security, low-maintenance common areas, and access to shared community amenities such as gyms, parks, and clubhouses, all of which lift your day-to-day quality of life.
For anyone ready to stop paying someone else’s mortgage and start building their own equity, the advisory team is available to discuss premium residential opportunities tailored to individual financial goals, as the first step toward true ownership.
Put simply, the rent you pay today builds someone else’s balance sheet, while the mortgage you pay builds yours. Equity, predictable costs, tax relief, security, and shared amenities all point in the same direction. The choice between paying a landlord and paying yourself is one every household eventually has to make.
If this breakdown was useful, hit the subscribe button so you stay connected to what comes next. Give the video a like if it helped, and turn on the notification bell so the latest updates reach you the moment they go live.”