A contract signed today, a price frozen the same day, and keys handed over a year or two later.
That sequence is the heart of what one property strategist calls the smartest entry point for anyone buying a first home. He has spent ten years in the business and advised hundreds of clients, and he has watched newcomers get caught between rising interest rates, stricter lender checks on applications, and prices that keep climbing, all at once. Of the paths available, he singles out off-the-plan buying, meaning the purchase of a new property before its construction is finished.
He measures that option against the older, established house. Such homes, he says, often conceal repair costs that slowly eat into a buyer’s savings. A new home secured before completion brings financial and lifestyle advantages that an aging property rarely matches. He organizes them under four headings: affordability, government support, protection against market swings, and design made for the future.
Cost leads the list, because first-time buyers name it as their biggest obstacle. In traditional markets, established homes frequently carry inflated prices, since demand for them is Immediate, and buyers end up with little leverage in negotiations. Off-the-plan deals take some of that pressure off in several ways. Developers commonly price competitively at the start, because early sales generate momentum and help fund the project. A buyer can fix the price now, whichever way the wider market moves later.
The payment schedule is different too. No one needs to produce the full purchase amount, or even a big lump sum, at the outset. The standard arrangement asks for a modest deposit, often around 10%, and the rest comes due only once construction reaches final completion. The strategist describes that interval as a runway. During months or even years of building, a buyer can continue saving, tighten the household budget, and Improve their financial standing, with no mortgage repayments weighing on them from the first day. For many young professionals and families, he argues, that extra room turns an Impossible dream of homeownership into a realistic goal.
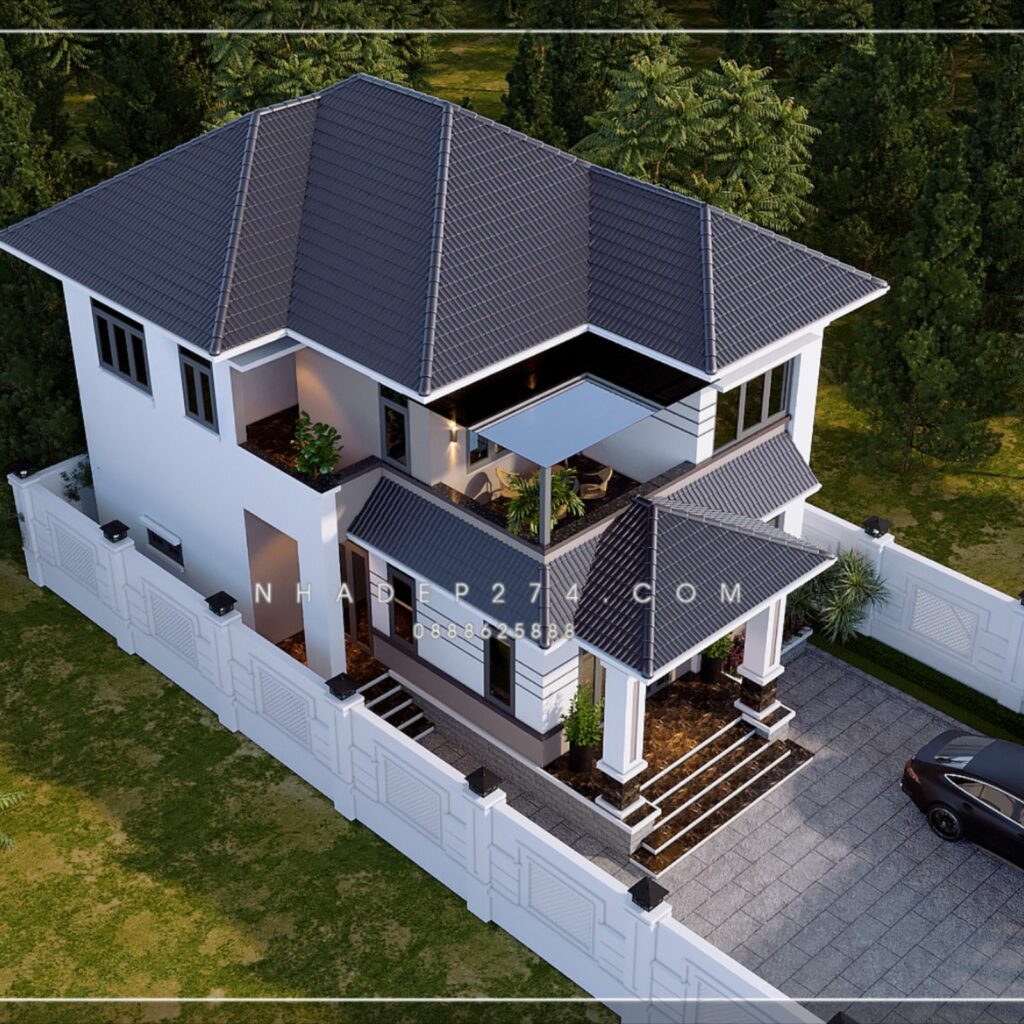
Government assistance forms the second pillar. Programs exist to narrow the gap for first-time buyers. The regulatory landscape shifts often, but key support systems remain in place and help newcomers get around the usual barriers to ownership. One of the most significant is the government-backed First Home Loan initiative. Banks routinely ask for a hefty 20% deposit, an amount that can take years, even a decade, of aggressive saving to gather. Specialized low-deposit frameworks cut that requirement sharply, in some cases to as little as 5%.
Pair one of those frameworks with an off-the-plan purchase, and the benefit compounds. The buyer lands a future home at today’s fixed valuation while putting up only a fraction of the capital initially. The wait to reach the first rung of the property ladder shortens considerably. The buyer is also sheltered from two lasting pressures: rents that keep rising and property prices that keep inflating.
Uncertainty is the third consideration, and it comes with every property cycle. Market corrections, interest rate adjustments, and sluggish economic conditions often make buyers hesitant to commit their money. The strategist sees a paradox in that, because those are exactly the conditions in which an off-the-plan purchase proves its resilience.
The mechanics explain why. Under an off-the-plan contract, the purchase price is set on the first day. Settlement waits until construction ends, frequently 12 to 24 months later, and the market keeps moving throughout that window. If property values climb in the meantime, the buyer’s asset may already carry added equity before the keys change hands. If the market stalls for a while instead, the locked-in contract price keeps the buyer from paying an inflated peak price. That built-in cushion protects the investment and provides a degree of long-term financial security that a traditional purchase with instant settlement cannot offer.
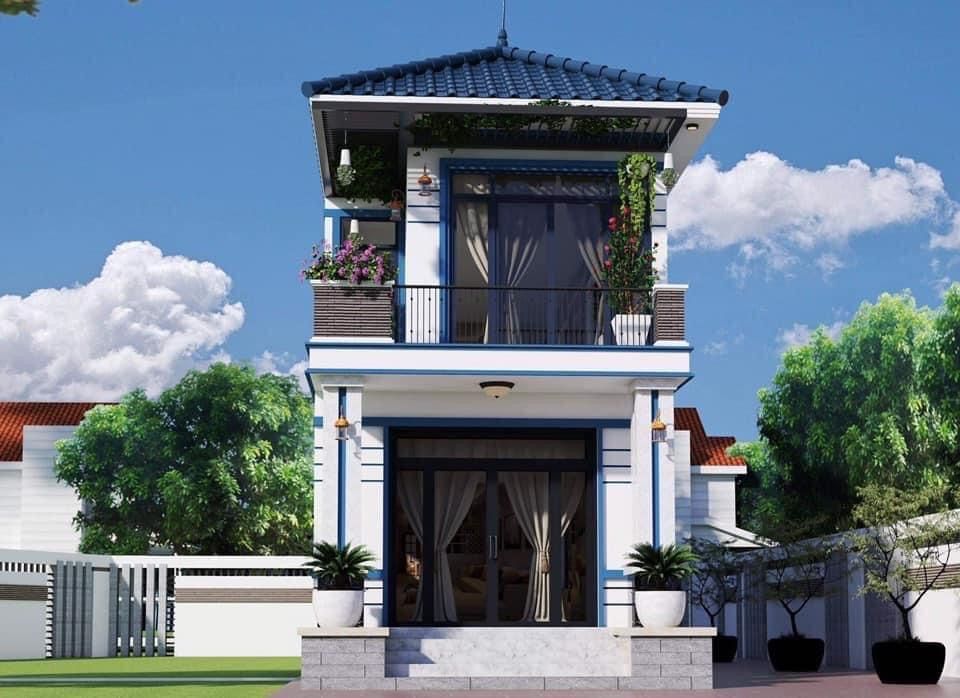
Money is only part of the picture, since a home is a deeply personal matter. Today’s buyers expect more from their living spaces than earlier generations did. They want energy efficiency, smart-home integration, minimalist aesthetics, and low-maintenance upkeep. Developers of modern off-the-plan projects understand those shifting preferences well. New developments therefore feature cutting-edge architectural design, double-glazing, high-grade insulation, solar power provisions, and sustainable building materials. Those elements Improve daily life, and they also reduce ongoing utility and maintenance costs significantly.
An older established property can offer a very different experience. Owners often face expensive renovations soon after moving in, unexpected plumbing failures, and costly structural upgrades. A home bought off-the-plan sidesteps those headaches. It complies with the latest building codes and comes with comprehensive developer warranties. It also stays highly attractive to future buyers or tenants should the owner’s lifestyle needs change down the track.
Taking a first step into the property market is undeniably intimidating, yet the strategist insists that the right strategy changes everything. Strategic financial planning, low-deposit lending options, protection against market swings, and the efficiency of modern architecture combine into a clear, structured pathway. That pathway leads toward long-term wealth creation and stable housing.
Four points carry the argument. A small upfront deposit and a long settlement window lower the cost of entry. Government-backed low-deposit lending shortens the road to ownership. A price fixed on day one offers protection while the market moves. And a new build brings modern design, current building standards, and developer warranties. Each answers a different pressure on first-time buyers, and together they explain why this route deserves serious consideration from anyone about to take that first step.
If this breakdown gave you something useful, hit the subscribe button so you don’t miss our next report. Give the video a like, too, so it can reach other people weighing the same decision. And turn on the notification bell, so the latest news lands in your feed the moment it’s published.”