Ten years of helping clients assemble large property portfolios have left me with one firm conclusion: real estate rewards patient, disciplined investors who execute well, and it punishes those who simply hope for the best.
Lasting wealth in this field depends on a durable long-term plan. It makes no difference whether you are buying a first home, expanding existing holdings, or preparing assets for retirement. A structured approach lets you tune out the daily churn of the market and keep advancing toward financial independence.
Every plan begins with a defined endpoint. Before you browse a single listing or speak with a lender, decide what the portfolio is supposed to deliver. The answer might be reliable passive income, equity that builds over decades, or commercial real estate financing to fund a business venture. That choice shapes every decision that follows. So does your time horizon, which could be five years or a thirty-year accumulation period, and so does your appetite for risk. Risk tolerance determines whether you lean toward steadier residential properties or higher-yield commercial ventures that carry more danger. Concrete milestones also help, since they convert loose aspirations into targets you can act on, such as earning three thousand dollars per month in net rental income within seven years.
Your own finances come next, and they deserve a hard look. Even a brilliant strategy collapses when your money is not lined up behind it. Before committing any capital, audit your personal balance sheet: liquid savings, recurring income, and existing debts. Lenders examine those same numbers, and your financial health determines which mortgage rates and commercial real estate loans you can reach. A detailed operating budget is essential. It should account for upfront costs such as down payments, closing costs, inspection fees, and legal charges, plus a cash reserve to absorb vacancies or emergency repairs. Your credit score needs active attention too. A score above seven hundred unlocks significantly better financing terms and lowers your borrowing costs over the long run. A qualified financial advisor can confirm that your property investments fit within your wider wealth management goals.
Then comes location. In the property sector, information is currency, and local conditions shift with economic changes, population growth, and infrastructure projects. Successful investors study regional data before they deploy money. They look for neighborhoods with sustained job growth, expanding school districts, and new commercial development. Appreciation ultimately follows supply and demand. Where housing inventory is limited and people are arriving at a strong pace, upward pressure builds on both home values and rental yields. Keep tracking employment figures, inflation trends, and regional economic forecasts to confirm that your target market can withstand economic stress over the long term.
A portfolio turns dangerous when too much of it sits in one place, so spread your capital across asset classes and regions. Doing so shields your wealth from downturns that strike a single locality. Rather than relying only on single-family suburban homes, consider a balanced blend of residential property, multi-family units, and commercial space. Geographic diversification protects the whole portfolio if a particular city or state hits an economic slowdown. You can also pair a buy-and-hold rental approach with selective fix-and-flip projects, which allows you to weigh near-term liquidity needs against long-term capital appreciation.
Once you own property, you are running an active business. Long-term profitability hinges on how well you manage the assets and keep them in good physical condition, and you must choose between handling the work yourself and hiring a professional property management firm. Self-management saves administrative fees, but it consumes a great deal of time through tenant relations, emergency repairs, and compliance regulations. Investors with multiple units, or those who want a truly passive experience, will find that a reputable management company’s percentage fee is money well spent. Whichever route you take, routine inspections and proactive maintenance budgeting keep small issues from growing into costly capital expenditures. That budgeting means setting aside roughly one to two percent of the property value each year.
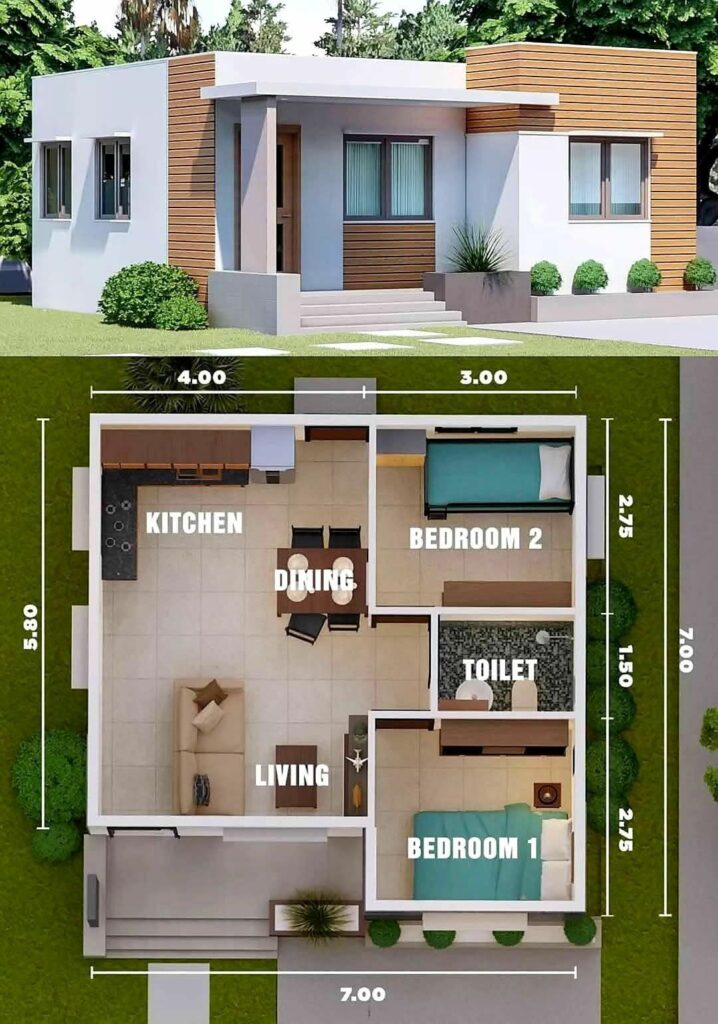
The market never stands still. Regulatory updates, economic cycles, and shifting consumer preferences keep reshaping the property landscape, and complacency is the chief enemy of long-term success. Staying informed through industry publications, networking events, and ongoing market analysis keeps you competitive. Adaptability could mean revising your acquisition criteria as mortgage rates fluctuate, or moving toward sustainable, energy-efficient housing developments. Either way, it keeps your portfolio resilient.
A plan that covers only the entry is unfinished. Knowing how and when you will liquidate or transition your assets matters as much as the original purchase. An exit could mean selling at a market peak to maximize capital gains, using a tax-deferred exchange to acquire larger commercial assets, or refinancing to pull out equity for the next venture. For those planning a generational wealth transfer, a clear estate plan drawn up with legal and tax professionals minimizes tax liabilities and ensures a smooth handover of assets to heirs.
Put together, clear objectives, sound handling of capital, thorough market research, and efficient operations are the elements that position an investor for lasting success. The question each investor still has to answer is whether the plan on paper covers every stage, from the first purchase to the final exit.
If this walkthrough changed how you think about your own approach, tap subscribe so the next one reaches you right away. Give the video a like if you found it useful, and switch on the notification bell so you catch the latest updates the moment they go live. And if you would like professional guidance shaped around your financial goals, reach out today to schedule a personalized portfolio consultation.”