Ten years in residential property.
Hundreds of families who came to him weighing the same decision. That is the background of the real estate professional behind this argument, and he says the usual way families frame the choice is too narrow. They put monthly rent next to a home loan EMI, see that renting looks cheaper and more flexible, and stop there. In his assessment, property is not just an arithmetic exercise. It is a long-term wealth strategy, an anchor for daily life, and a hedge against inflation, all in one.
He says the case is strongest in high-demand micro-markets like Tripunithura and the wider Kochi metropolitan region, where the structural advantages of getting onto the property ladder are plain to see. His conclusion: over the long run, buying an apartment is almost always the smarter move.
The core difference, he explains, is what happens to the money. Rent is a terminal expense. Each payment buys thirty days of housing and leaves nothing behind. A home loan EMI, by contrast, works as a form of forced savings. Part of every payment reduces the principal and builds equity, and as the property gains value, that equity compounds. Instead of funding a landlord’s investment year after year, the buyer holds a tangible asset that belongs to the family and its heirs. Buying builds net worth through equity accumulation and property appreciation, while renting produces no financial return.
Predictability is the second advantage. Rent keeps moving, and almost always upward. When local demand surges and neighborhoods mature, landlords routinely raise prices, and tenants must either absorb the increase or face the disruption of relocating. A purchase financed with a fixed-rate home loan locks in the core housing payment for the long term. Rents across the city may rise with inflation, but the EMIs stay entirely predictable. When the loan tenure ends, the owner enters a phase of rent-free, mortgage-free living, which sharply reduces expenses in retirement.
Government policy tilts the same way. He notes that governments universally favor homeownership over tenancy, using structured tax incentives designed to encourage capital formation. Renters get no deductions for their monthly spending. Homeowners can claim substantial tax breaks on both the interest and the principal portions of loan repayments. These statutory deductions lower the annual tax liability and cushion the cost of acquiring the property. A clean repayment record also builds a strong credit history, which can open the door to favorable lending terms for future entrepreneurial or personal financial goals.
An apartment also keeps working when life changes. Suppose a career takes the owner to another city, or the family eventually moves up to a larger home. The apartment does not have to sit empty. In thriving residential areas like Tripunithura, rental demand stays consistently high because of proximity to commercial hubs, educational institutions, and infrastructure corridors. A well-located 2 BHK or 3 BHK apartment becomes a ready-made asset that can generate steady passive rental income. That income can often cover the initial investment costs and offers protection against future market shifts. He calls this versatility one of the greatest hidden perks of ownership.
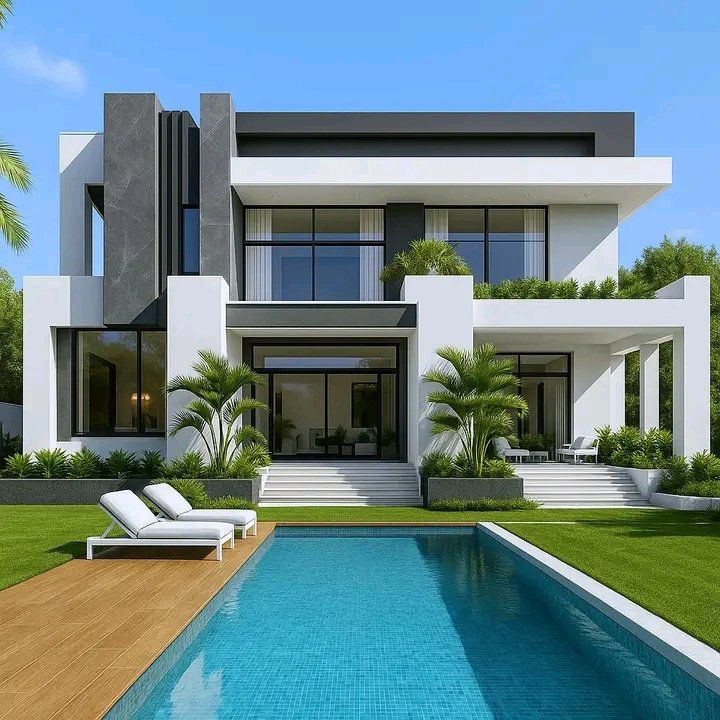
Then there is the question of how families actually live day to day. Standalone rental houses often lack the integrated ecosystem that modern urban households need. Modern gated communities supply a complete lifestyle package that independent homes cannot match. A project by a top builder in Kochi, he says, gives residents a secure, well-managed environment, with 24/7 security surveillance, power backup, landscaped parks, state-of-the-art fitness centers, and community clubhouses. That mix of physical security and social infrastructure Improves a family’s quality of life and protects the value of the investment. It also explains why apartments are gaining ground on independent houses: they balance security, shared amenities such as gyms and parks, lower individual maintenance burdens, and strategic locations within fast-growing urban corridors.
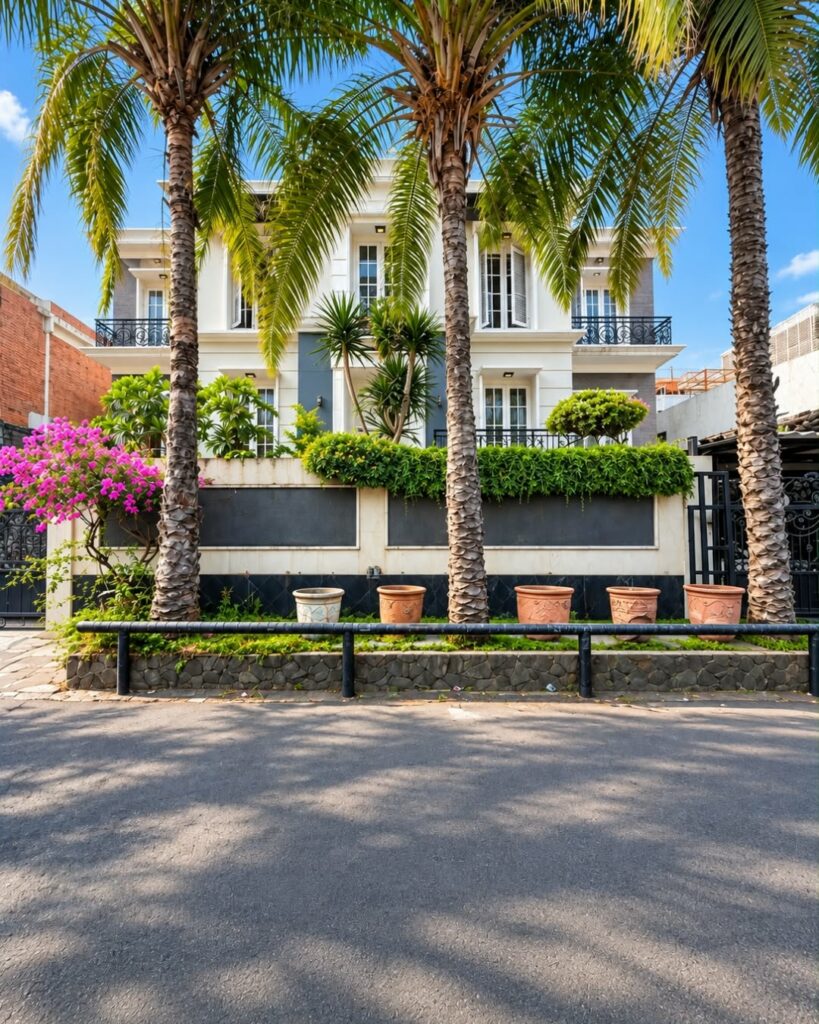
Control over the space is the last piece. Renters, in his words, live with invisible handcuffs. Knocking down a wall to create an open-plan kitchen is unlikely to be approved. Bespoke accent walls, premium hardwood flooring, or customized smart-home lighting fixtures all require permission, one small change at a time. Even when approved, the Improvements stay behind once the lease expires. Ownership reverses all of this. A premium apartment in Tripunithura is a blank canvas that can be shaped around the owner’s lifestyle. Fixtures can be upgraded, interiors overhauled, and high-end appliances installed, all chosen for personal comfort and without checking in with a landlord. Ownership also brings stability, creative freedom, and protection against unpredictable rent hikes.
For him, the decision finally comes down to long-term vision. People who value financial predictability, asset creation that passes across generations, and the peace of mind of a permanent home will find that stepping onto the property ladder is the clear winner. He points to Siddhi Homes, which builds premium living spaces engineered for comfort, security, and strong future appreciation. The company invites buyers to explore its latest portfolio of apartments for sale in Tripunithura, as a first step toward owning a home that is truly theirs.
The comparison comes down to a simple contrast. Renting covers the next thirty days. Buying builds equity, steadies housing costs, and creates an asset that can keep working for the owner and the owner’s heirs. For any family at that spreadsheet, the real question is what each payment leaves behind.
If this report helped you think through the decision, tap the subscribe button so the next one finds you right away. Give the video a like to let us know it was worth your time, and switch on the notification bell so our latest stories reach you the moment they go up.”