A one-year warranty on cosmetic defects, paired with a ten-year guarantee on structural integrity: for one agent with a decade of experience steering clients through their purchases, that combination explains much of why a newly built home can stretch an entry-level budget further than almost any other option.
The agent’s argument rests on four pillars: upkeep, accountable builders, strict safety and compliance standards, and financing flexibility. Each speaks to a concern that first-time buyers raise constantly, and the concerns are well founded. Anyone entering the market for the first time has to weigh interest rates that keep shifting, tight lending criteria, and property values that never stay put. There is also a practical constraint. A demanding career, personal relationships, social obligations, and fitness goals already fill a first-time buyer’s calendar, leaving almost no room for DIY projects or surprise repairs.
Start with upkeep, which affects day-to-day life more than most buyers expect. Established houses can hide costly trouble, including aging plumbing, deteriorating roofs, and outdated wiring, and any one of them can force an urgent and expensive fix. A new build works from the opposite premise, because it is designed around fast-moving, contemporary routines. Its builders use cutting-edge manufacturing methods and high-grade materials engineered to withstand ordinary wear and tear. Surfaces are streamlined so they wipe clean easily, and the fixtures and energy-efficient appliances are selected for durability.
Warranties stand behind all of it. New properties usually carry robust builder warranties, often one year of coverage for cosmetic defects and ten years for structural integrity. This tiered arrangement removes most of the financial dread that comes with unexpected repairs. Instead of tracking down plumbing leaks or repainting decaying weatherboards on a free weekend, an owner can spend that time and energy enjoying the investment and settling into a vibrant new community.
The second pillar is the team that does the building. Buying off-plan, meaning while construction is still underway, requires trust in the development team. Established, reputable builders enforce rigorous quality control protocols, and they depend on long-standing partnerships with certified subcontractors, specialized engineers, and premium material suppliers. Dealing with trusted developers brings valuable predictability to the whole transaction.
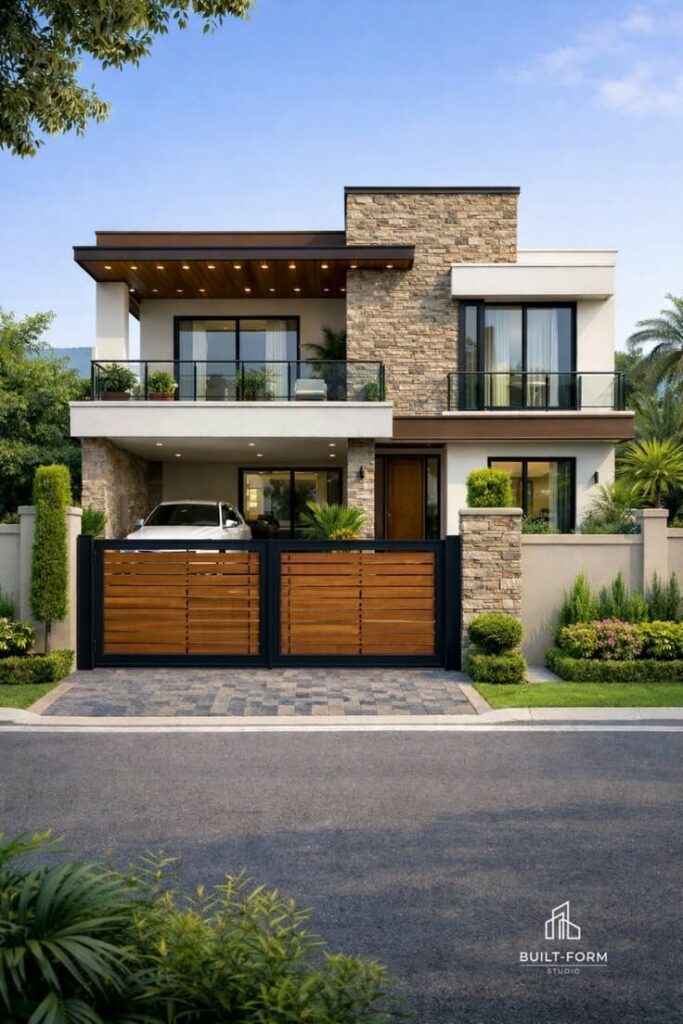
The paperwork reinforces that predictability. Contracts are transparent, with clear milestone schedules and fixed prices that shield a buyer’s budget from unexpected cost overruns. Logistics are coordinated, and dependable delivery timelines let buyers arrange lease terminations, mortgage funding, and moving plans without friction. The relationship also continues after the sale closes. Professional aftercare teams remain available and promptly handle minor adjustments while the new structure settles naturally into its foundation. That professional accountability takes the guesswork out of a residential investment, and it gives buyers firm reassurance that their capital rests on industry-leading craftsmanship.
Safety and compliance form the third pillar. Careful buyers place structural integrity, safety, and environmental sustainability near the top of their priority lists. Older properties can harbor legacy compliance problems, and updating them to meet today’s legal benchmarks may require costly remediation. Modern residential developments are governed by rigorous statutory frameworks instead. Comprehensive building codes require full compliance in structural engineering, fire safety, weather tightness, and thermal efficiency.
A new-home buyer benefits from several layers of oversight. Independent municipal and private certifiers inspect every stage of the work, from the foundation pour through the final interior finishes. Contemporary engineering allows the structure to handle regional climate swings while keeping indoor comfort intact. Designers also plan the infrastructure with the future in mind, so outdated electrical grids and inadequate plumbing layouts are avoided altogether and the asset does not become obsolete too early. Because the house follows current legal codes so closely, it is safe, highly efficient, and exceptionally attractive on the secondary market if the owner later decides to upgrade or sell.
Financing is the fourth pillar, and it is where the advantage shows up first. New builds carry economic benefits that tilt strongly toward people buying for the first time, and the biggest is leeway on lending limits. In many housing markets, regulations exempt new builds from strict Loan-to-Value Ratio (LVR) restrictions. A buyer of an established property is often expected to bring a large down payment, while qualifying for a new build can require a far smaller deposit. With that hurdle lowered, would-be owners can leave the rental market and become homeowners much sooner.
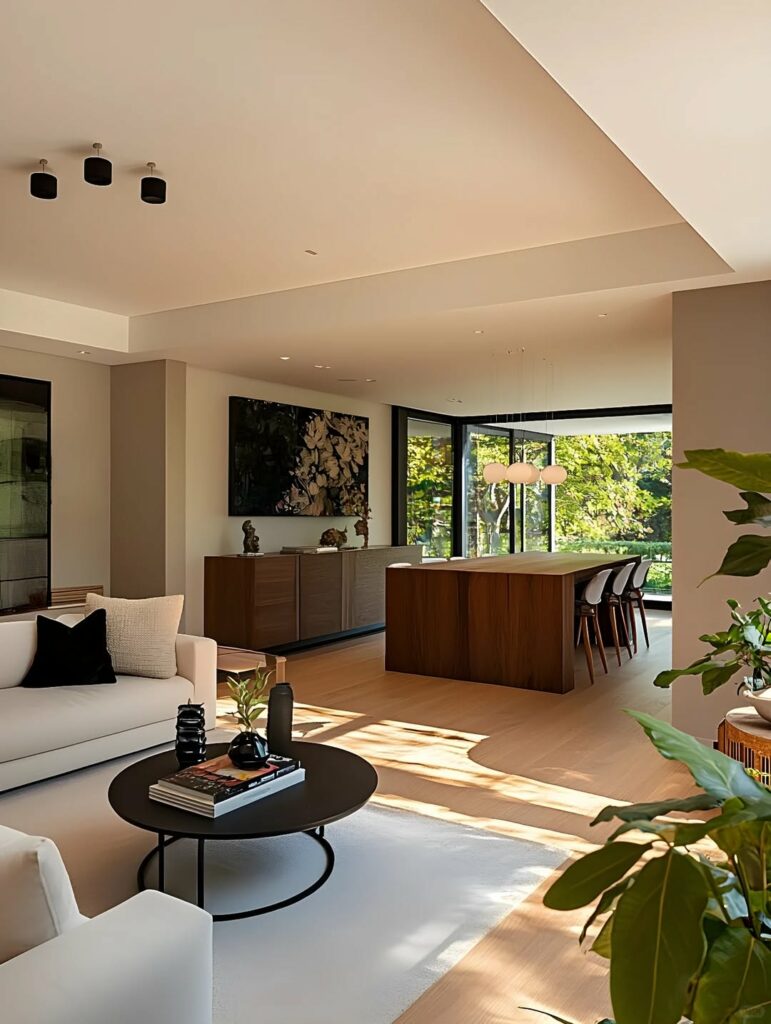
Location and long-term value strengthen the financial picture. Master-planned developments filled with brand-new houses usually rise in expanding suburban corridors, where modern infrastructure, broader public transit networks, and shopping amenities arrive as part of the package. Growth areas of this kind naturally post stronger capital appreciation over medium-to-long investment horizons. Energy performance adds another layer. New homes come with state-of-the-art insulation, double-pane glass, and high-efficiency HVAC systems, so monthly utility bills fall dramatically. Those recurring savings ease the transition into ownership and build wealth year after year.
Taken together, a new construction property delivers low-maintenance convenience, financial flexibility, strict safety compliance, and long-term capital growth. Choosing a home built for contemporary living protects a buyer’s finances and secures a comfortable, high-performing asset suited to the future. Buyers ready to look at available developments and compare tailored financing options can contact an expert advisory team and book a personalized consultation, a step that lets them claim a place on the property ladder with total confidence.
In the end, the agent’s case comes down to four risks removed from a first purchase: unpredictable financing, substandard construction, unreliable builders, and costly maintenance. For a buyer weighing an older house against a new one, those are the points where the two options part ways most clearly.
If you value clear, fact-based reporting like this, subscribe to the channel so the next video reaches you the moment it goes live. Give this one a like if it helped, and switch on the notification bell so the latest news is waiting for you as soon as it is published.”